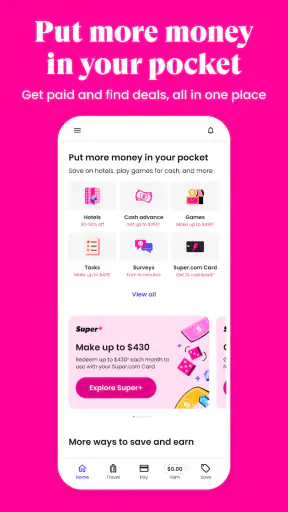
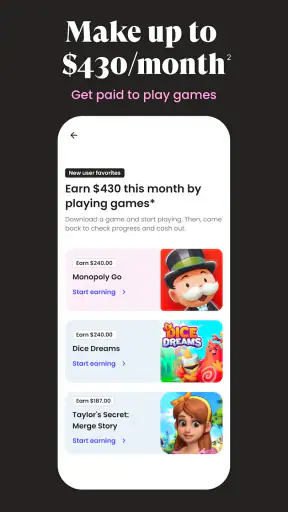
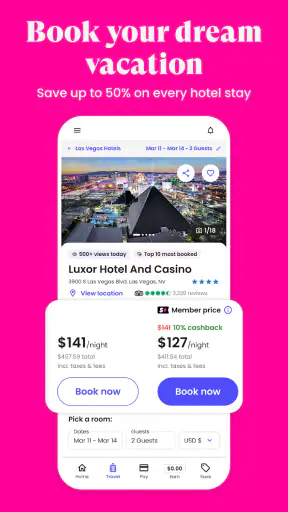
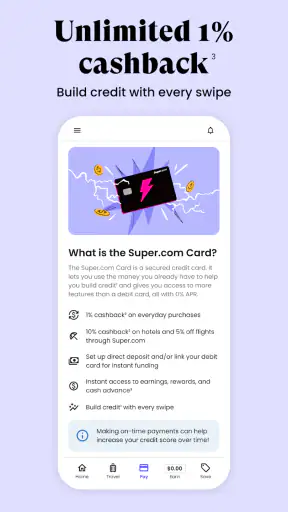
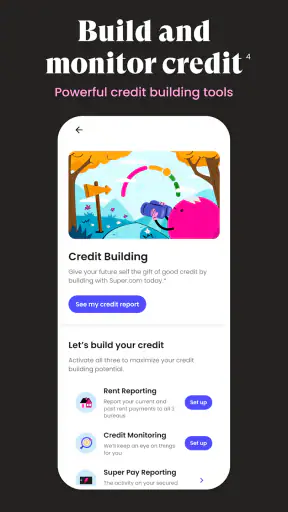
I approached Super.com-Cash Advance, Travel as a practical finance app rather than a single-purpose travel tool. The idea is to bring several money-related tasks into one place, including ways to save, earn, arrange travel, and access cash-related services. That combination makes it more interesting than a standard budgeting app, but it also means you need to pay attention to which part of the service you are actually using at any given moment.
In my experience, the appeal is convenience. Instead of switching between a travel app, a savings service, and another financial tool, Super.com tries to make those activities feel connected. I can see why that approach attracts people who want a simpler money routine, especially when a trip, an unexpected expense, and everyday spending all overlap. At the same time, I would not treat it as a complete replacement for a bank account or as a universal answer to financial planning.
How Super.com feels in its current form
The app sits in the finance category and is free to install, with an Everyone age rating. Its public presence is already substantial: it has passed one million installs and holds a 4.5 average from roughly thirty-one thousand ratings, alongside around seven thousand reviews. Those figures suggest that it has reached well beyond a small experimental audience, although popularity alone does not tell me whether every feature suits every user.
The developer is Super, previously known as SnapTravel. That history matters because it helps explain the app’s travel connection. The current product is broader than a hotel-focused experience, placing travel alongside money-saving and earning tools. I would describe it as a financial hub with a travel side, not simply a travel booking app with a payment feature attached.
The current Android version is 14.10.8, and the app requires Android 10 or newer. For someone using a reasonably recent phone, that requirement should not be surprising, but it is worth checking before planning to rely on the app during a trip. A finance app is most useful when it is available at the moment an expense appears, so compatibility is more important here than it would be for a casual game.
The first practical question is what you want from it. If your goal is to explore several money services in one interface, Super.com is worth investigating. If you only want a simple spending ledger, a dedicated budgeting app may feel clearer. If you only want to compare hotels, a conventional travel service may involve less financial context and fewer decisions. The all-in-one design is its main attraction, but also the reason the experience can feel broader than necessary.
A realistic everyday use case
Imagine I am preparing for a weekend away while trying to keep my monthly spending under control. I might use the travel area to research accommodation, look for a way to reduce the cost of the booking, and then check whether one of the app’s money features could help me manage the remaining budget. The value is not that every step becomes automatic; the value is that I can keep the trip and the financial consequences in the same place while making decisions.
That workflow is particularly useful for someone who tends to lose track of the total cost of travel. A room price is only one part of a trip. Transport, meals, deposits, and last-minute purchases can matter just as much. Keeping the travel decision beside the saving or cash-related side of the app encourages me to think about the whole expense rather than focusing on the most attractive headline price.
There is also a less obvious benefit to separating “saving” from “borrowing” in my own thinking. An offer that reduces a cost is not the same as money that has to be repaid or managed later. I would use Super.com to compare those possibilities, but I would not assume that a convenient cash option is automatically the cheapest solution. The app can bring the choices together; I still need to judge their consequences.
What the combined design does well
The strongest part of the concept is the way it connects short-term decisions. Travel often creates an artificial deadline, and that can lead people to make hurried financial choices. Having travel and money tools together may reduce the need to jump between several services, copy details from one app to another, or forget where a particular offer came from.
I also appreciate that the product is not limited to one narrow financial habit. Some people want to save on a purchase, others want to earn through an available feature, and others are looking for help with a temporary cash gap. Those needs are different, but they often occur in the same household. A single app can be convenient for comparing options, especially for users who do not want to maintain a collection of specialized services.
Another useful habit is to open the app before committing to a travel purchase, not after. That gives me a chance to compare the available route, inspect the total, and decide whether the financial tool is genuinely helpful. Opening it only when I am already short of money encourages reactive decisions. Used earlier, it works better as a planning aid.
How the product has evolved
The move from SnapTravel to Super reflects a broader product direction: travel remains part of the identity, but the service now presents itself as a wider way to manage money around everyday life. I see that evolution in the name and in the way the app is positioned. It is no longer sensible to judge it only by asking whether it is a good place to find accommodation.
The release date shown for the app is June 27, 2019, while the current version is 14.10.8. That combination points to an established product that has continued through multiple iterations rather than remaining a one-off travel utility. I would still separate that evidence from assumptions about future additions. A newer version number tells me the app has developed over time; it does not guarantee that every feature will change in a way I personally prefer.
For existing users, the broader direction can be helpful because it creates more reasons to return. Someone who first arrived through the travel side may now find additional financial tools relevant between trips. The trade-off is that the app can feel less focused than it did when travel was the main reason to open it. A user who wants one very clear task may need to spend more time finding the right section.
This is where I think the latest version matters most in practical terms. Product evolution is not only about adding visible functions; it is also about reorganizing how people reach them. When an app expands from travel into several financial areas, navigation and explanations become especially important. I would judge the current release by how quickly I can understand the choices in front of me, not just by counting how many services appear on the screen.
What existing users should keep in mind
If you have used the older SnapTravel identity, the biggest adjustment is conceptual. The service now asks you to think of it as more than a place to arrange a trip. That can be a welcome expansion if you already want savings or earning tools. It may be less welcome if you preferred a narrowly focused travel experience and do not want financial features competing for attention.
My advice is to establish a simple personal routine. Use the travel section when you are comparing a trip, review saving opportunities before paying, and treat any cash-related option as a separate financial decision. Do not let the fact that everything appears inside one app blur the difference between reducing a cost and taking on an obligation.
I would also keep my normal financial records outside the app. That is not a criticism of Super.com; it is a sensible safeguard whenever one service covers several areas. A separate bank statement, calendar reminder, or basic note can help me remember what I selected and when I need to review it. The all-in-one interface is convenient, but convenience should not replace personal oversight.
For a household, another practical approach is to decide who is responsible for checking the details before a booking or financial action is completed. Travel decisions often involve more than one person, and a shared understanding of the total cost prevents the app from becoming a place where one attractive option is accepted without discussion. Super.com can support the research, but it cannot make that household decision for me.
Where the experience still has limits
The broad scope is also the main source of friction. An app that combines travel, saving, earning, and cash services has to explain several different types of decision. That can make the experience feel busier than a dedicated alternative. If I am in a hurry, I may prefer a specialist app that does one job with fewer distractions.
I would also avoid assuming that an advertised financial option is automatically suitable because it appears beside a travel deal. The timing may be convenient, but convenience and value are separate questions. Before using any cash-related service, I would read the terms carefully, understand the repayment expectations, and compare the total consequence with other options already available to me.
There is a similar issue with travel comparisons. A lower visible price may not represent the complete cost of the trip once conditions, extras, or changes are considered. I would use the app to discover and compare possibilities, then inspect the final details before confirming anything. That extra step is essential when the purchase is connected to a wider financial choice.
People who need detailed long-term budgeting may find the app too general. Someone tracking categories, recurring bills, shared accounts, or a multi-year savings plan may be better served by a dedicated budgeting system. Super.com makes more sense for short- and medium-term decisions around spending, travel, and available money tools than for replacing a full financial planning setup.
I would also skip it if I strongly prefer to keep travel and personal finance completely separate. The integrated model is the point of the app, so users who dislike cross-category services may find the design uncomfortable rather than useful. Likewise, anyone looking only for a traditional bank relationship should compare the app with established banking options instead of assuming that an all-in-one finance app provides the same role.
Three smarter ways to use it
First, I would use Super.com as a pre-purchase checkpoint. Before booking, I would write down the total amount I am willing to spend, inspect the available saving route, and decide whether the trip still fits that limit. This prevents the travel section from becoming a source of impulsive upgrades. The important insight is to set the boundary before browsing, because attractive options can quietly change the original plan.
Second, I would separate immediate savings from delayed costs. If one feature helps lower the price today, I would treat that as a direct benefit. If another feature provides cash that must be managed later, I would record it as a future responsibility. Keeping those two results in separate mental columns is a simple way to avoid mistaking access to money for an actual saving.
Third, I would use the app at two different times: once during planning and again after the purchase or trip arrangement. The first visit is for comparison; the second is for checking what I chose and making sure I have not forgotten an important detail. This two-stage workflow is more reliable than opening the app only when I need emergency assistance.
A fourth useful approach is to compare its convenience with the cost of complexity. If using one app saves me time without changing my financial decision, that is a genuine advantage. If the combined layout makes me spend longer understanding an offer than I would spend with a specialist service, the convenience has disappeared. The right choice depends on how much I value consolidation.
Who will get the most from it
I think Super.com is best suited to people who travel occasionally, actively look for ways to reduce expenses, and appreciate having several related tools in one account or interface. It can also suit users who want to explore financial options without installing a separate app for every small task. The free entry point makes it easy to test whether that broader approach fits a personal routine.
It is less convincing for someone who already has a trusted travel service, a carefully designed budget, and a separate system for handling unexpected expenses. In that situation, adding another app may create duplication rather than value. I would only keep it if the combination provides a clear benefit, such as easier travel planning or a useful saving workflow that my existing tools do not offer.
New users should begin with one purpose instead of trying to understand the entire product at once. I would start by exploring the travel or saving side, learn how the information is presented, and only then examine cash-related services. This makes it easier to judge each part on its own merits and reduces the chance of making a rushed financial choice simply because the option is visible.
What I would watch going forward
The most important thing to watch is whether the broader product remains easy to understand as it evolves. More financial tools can be valuable, but only when the app makes the differences between them obvious. I would look for clear explanations, straightforward navigation, and a clean separation between savings, earnings, travel purchases, and cash access.
I would also pay attention to how well the travel heritage supports the newer finance direction. The app has a distinctive advantage when the two sides genuinely help each other: planning a trip should make the money tools more relevant, and the money tools should make travel decisions easier to evaluate. If the sections feel unrelated, the all-in-one promise becomes less persuasive.
My overall view is positive but measured. Super.com is an unusual finance app because it connects travel with broader money services instead of forcing me to choose one narrow purpose. Its established history, current 14.10.8 release, free availability, and strong public reception make it reasonable to try, especially for users interested in travel savings and flexible financial tools.
Still, I would use it as a decision-making companion, not as my entire financial foundation. The best results come from comparing options, reading the details, and keeping track of future responsibilities outside the excitement of a travel purchase. Its real strength is convenience with context, but its real weakness is the temptation to treat every convenient option as equally beneficial. If you want one place to explore travel and money choices, I recommend giving it a careful trial. If you want a focused budget, a conventional bank, or a specialist travel service, another app may serve you better.


